Most buyers focus on the deposit, loan approval and moving costs first. Then transfer duty appears in the figures, often as one of the largest upfront amounts attached to a New South Wales property purchase.
Many people still call it stamp duty. In NSW, the official term is transfer duty, and it usually needs to be dealt with before settlement can go ahead.
What transfer duty means for NSW property buyers
Transfer duty is a state tax charged on certain property transactions and documents in NSW. For home buyers, it most commonly applies when purchasing residential property, though its reach is wider than many people expect.
It is not limited to a standard house purchase. Duty can also apply when someone acquires property without paying for it, including by gift, declaration of trust or a change in beneficial ownership. That makes it a tax tied to the transfer of value and ownership, not just a sale contract.
Common transactions that may attract transfer duty include:
- homes and units
- investment properties
- vacant land
- farming property
- commercial or industrial property
- businesses that include land
- gifted property interests
This is why transfer duty deserves a place in the budget from day one, not as an afterthought once finance is approved.
Who pays transfer duty in NSW
In NSW, transfer duty is paid by the purchaser or transferee. It is not paid by the seller or transferor.
That sounds simple, yet it is a point many first-time buyers get wrong. The seller may hand over title, but the buyer is the one responsible for the duty liability. Even if a conveyancer, solicitor or another party arranges the payment, the legal responsibility still sits with the purchaser.
That responsibility matters because an unpaid duty amount can interfere with settlement. In a standard transfer, settlement cannot proceed if duty has not been paid or properly accounted for. So while transfer duty is a tax issue, it becomes a settlement issue very quickly.
When transfer duty is due before settlement
The general NSW rule is strict. For most purchases, transfer duty is due by the earlier of settlement or three months after the contract date. For transfers that do not arise from a sale contract, the relevant date may instead be three months from the transfer form date or the deed date.
That timing can catch buyers off guard, especially in shorter settlements. If settlement is set for six weeks after exchange, duty will usually need to be paid by settlement, not at the end of the three-month period.
A quick timing guide makes it easier to see.
| Transaction type | Usual duty deadline | What buyers should know |
|---|---|---|
| Standard property purchase | Earlier of settlement date or 3 months after contract date | Duty usually needs to be ready before settlement |
| Transfer without a sale contract | Within 3 months of the transfer form date | Market value may still matter |
| Dutiable deed | Within 3 months of the deed date | The document date sets the timing |
| Eligible off-the-plan purchase | Earlier of completion or 12 months after contract signing | A deferral may apply if the contract meets the rules |
A buyer who leaves duty to the last minute can run into avoidable pressure. Funds need to be available, concessions need to be claimed correctly, and the assessment needs to match the transaction details.
How NSW transfer duty is calculated on dutiable value
Transfer duty in NSW is calculated on the dutiable value of the property. This is the higher of the purchase price or the market value.
That rule is especially relevant where the parties know each other, where a property is transferred as a gift, or where the contract price is not a reliable measure of value. In those situations, the market value can drive the calculation even if little or no money changes hands.
The rates are not a flat percentage. NSW uses a sliding scale, so the amount rises as the dutiable value increases. For the 2025 to 2026 financial year, rates start at $1.25 per $100 for values up to $17,000 and rise to $5.50 per $100 above $1,240,000. Once the premium threshold is crossed, the higher rate applies to the relevant portion.
Rates and thresholds are adjusted each year in line with CPI, so buyers should always check current Revenue NSW figures before relying on an older estimate. A property that sits near a threshold can produce a different result from one financial year to the next.
A rough estimate is useful early on, though the final duty amount should be checked against the signed contract and the current scale. Small errors in value, contract date or concession eligibility can change the figure.
First home buyer transfer duty concessions in NSW
For eligible buyers, the First Home Buyers Assistance Scheme can reduce transfer duty significantly, and in some cases remove it altogether.
For purchases with a liability date on or after 1 July 2023, eligible first home buyers purchasing a new or existing home valued at $800,000 or less may receive a full exemption from transfer duty. Eligible buyers purchasing vacant land valued at $350,000 or less may also receive a full exemption.
Above those full exemption figures, concessional duty may still apply within the current Revenue NSW threshold ranges. That means some first home buyers will not pay the full standard amount even where the purchase price sits above the exemption cut-off.
The main points are:
- Full exemption for homes: eligible first home buyers may pay no transfer duty on a new or existing home valued at $800,000 or less
- Full exemption for vacant land: eligible first home buyers may pay no transfer duty on vacant land valued at $350,000 or less
- Concessional duty: reduced duty may apply above those figures within the current published scheme limits
This can make a major difference to cash flow. A buyer who qualifies may be able to keep more funds available for legal costs, lender fees, moving expenses or early repairs after settlement. As one practical example, Cloud9 Roofing explains how storm-damage insurance claims are usually handled — including excesses, assessor timeframes and temporary repairs — factors that can influence a new owner’s cash flow soon after settlement.
Because the scheme is tied to current rules and value thresholds, it is wise to check eligibility before exchange, not just before settlement. A concession that is assumed but not available can leave a sudden funding gap.
Off-the-plan transfer duty deferral in NSW
Off-the-plan purchases follow a different timetable in some cases, which can be valuable for buyers trying to manage cash over a longer construction period.
In NSW, liability for transfer duty on an eligible off-the-plan purchase can arise at the earlier of completion or 12 months after the contract is signed.
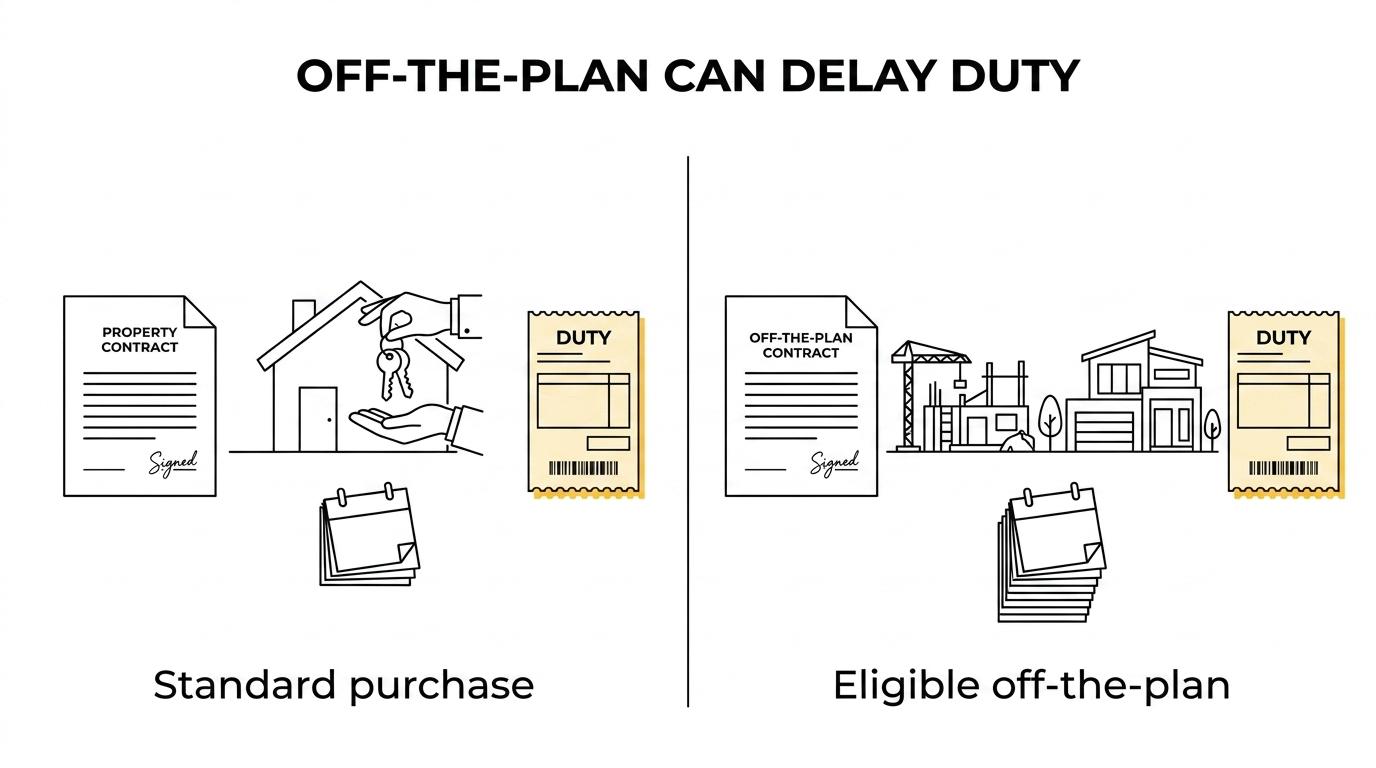 This is often described as an off the plan deferral.
The deferral is not automatic in every contract. To be eligible, the land contract must state that a home will be built on the land before settlement. If the transaction qualifies, the buyer may have longer before duty needs to be paid than under the usual three-month rule.
That extra time can be helpful.
It gives some buyers a chance to keep funds in place during construction rather than paying duty soon after exchange. Still, the timing needs close attention. If transfer duty is paid more than three months after the contract date without a valid deferral arrangement, Revenue NSW may charge interest and penalty tax.
Off-the-plan buyers should also remember that a long settlement does not always mean duty can wait until handover. The contract terms and the Revenue NSW rules need to match.
Why transfer duty should be part of your purchase budget early
Transfer duty is often one of the biggest non-loan costs in a property purchase. For buyers stretching to meet a deposit, it can be the amount that decides whether a deal is comfortable or too tight.
That is why budgeting early matters. A clear estimate helps buyers judge their real cash requirement, not just the purchase price and deposit. It also reduces the risk of scrambling for funds in the final days before settlement.
A practical approach usually looks like this:
- Estimate duty as soon as the purchase price is known.
- Check whether any exemption, concession or off-the-plan deferral may apply.
- Confirm the due date from the contract date and proposed settlement date.
- Make sure the payment funds will be available in time.
- Ask your conveyancer or solicitor to verify the assessment details before settlement is booked.
Buyers often feel more confident once these figures are pinned down. The uncertainty drops away, and the transaction starts to feel manageable.
How a conveyancer helps with transfer duty in NSW
Transfer duty is a tax issue, but in practice it sits right in the middle of conveyancing work. The contract details, the property value, the identity of the parties, the settlement date and any available concession all feed into the final result.
A conveyancer can check whether the transaction is straightforward or whether a market value issue, trust arrangement, related-party transfer or first home buyer claim needs closer attention. That early review can prevent delays later when settlement is close and the timetable is less forgiving.
Many buyers also benefit from having someone track the dates that matter most:
- contract date
- liability date
- settlement date
- transfer form date, where relevant
- concession or deferral application timing
For NSW buyers, the main message is simple. Transfer duty is usually paid by the buyer, it often needs to be ready before settlement, and the amount depends on the dutiable value and the current rates. Where a first home buyer concession or off-the-plan deferral is available, the savings or timing relief can be substantial, but only if it is checked and handled early.